To improve your credit score, do four things in this order: check all three credit reports for errors, dispute anything wrong, bring every payment current automatically, and cut your card balances down. That sequence usually moves a thin or damaged file more in 90 days than any product you can buy.
This guide is written for readers starting from a low score, a nearly empty credit file, or a report damaged by collections or identity theft. It also covers readers whose finances were tangled with a former partner, where joint accounts keep damaging a score long after the breakup.
A note before you start: score models differ, rules vary by state, and this is general information rather than individual financial advice. Your creditor or a nonprofit credit counselor can look at your specific situation.
Table of Contents
- What You Need
- Step-by-Step
- 1. Check Your Credit Reports for Errors
- 2. Dispute Accurate Reporting You Do Not Recognize
- 3. Bring Automatic Payments Current
- 4. Reduce Card Balances: The Fastest Way to Improve Your Credit Score
- 5. Use a Small List of Credit Responsibly
- 6. Request a Limit Increase When It Fits Your Situation
- 7. Wait for Results and Prevent New Negative Entries
- Common Mistakes
- How to Maintain Your Credit Score After the 90 Days
- Frequently Asked Questions
What You Need
Before changing anything, gather four things. Most of the work in this plan happens on paper, and doing it in order saves you from fixing the same problem twice.
- Your three reports. Go to AnnualCreditReport.com, the only federally authorized site for free reports, and pull a copy from Equifax, Experian and TransUnion. Each bureau has its own file.
- Your score numbers. Write each one down with the date and the model name. The number in your bank’s app is often a different model than the FICO score a mortgage lender pulls, which is why the two can disagree.
- Recent statements. Twelve months of credit card and loan statements lets you confirm balances, due dates and minimum payments against what the report says.
- A written list of what you owe. Every revolving balance and every installment balance, including cards where you are an authorized user only.
Keep this list where you check statements. You will use it in the third step to make sure every payment, including rent, utilities and phone bills, has a working automatic schedule attached.
Step-by-Step
The plan runs seven steps across roughly 90 days. Which steps matter most depends on why your score is low, so use the five factors below to decide where to put your effort first.
| Factor | How much it counts | The action that moves it |
|---|---|---|
| Payment history | 35% | Automatic payments on every account, including rent and utilities where reporting is available |
| Amount owed | 30% | Lower reported balances before your statement date closes |
| Length of credit history | 15% | Keep the oldest account open, however small the limit |
| New credit | 10% | Few applications in a short window |
| Credit mix | 10% | A revolving account and an installment loan, if you can carry both |
The weights come from the FICO model most lenders use, published by myFICO. VantageScore, used by several card issuers, weights its own way, which is one reason two scores can sit far apart while both are technically correct.
1. Check Your Credit Reports for Errors
Start at AnnualCreditReport.com and download all three reports rather than only the one tied to a card you hold. Look for a wrong address, an old phone number, accounts that appear twice, debts you already paid, and collection entries for accounts you have never heard of.
Compare the three files line by line. A single missed payment often shows up at one bureau only, which is exactly why lenders check more than one.
2. Dispute Accurate Reporting You Do Not Recognize
If a real account appears that is not yours, treat it as possible identity theft rather than a clerical error. Dispute it with the bureau and contact the company that supplied the information, called the furnisher, because the furnisher is the only party that can pull the record.
Keep copies of everything you send: the report page, your dispute letter, your identity documents and any proof of payment. The CFPB explains on consumerfinance.gov that an investigation normally takes about 30 days, and that a confirmed error must be corrected or removed.
Legitimate accounts you do not recognize because nobody told you about them are a different case. Get documentation from the creditor, then decide whether paying, settling or leaving it alone helps you more.
3. Bring Automatic Payments Current
Payment history carries the most weight of any factor, so this is where a damaged file gains the most. Set automatic payments for the full statement balance or at least the minimum on every account, and turn on alerts as a second layer.
Confirm the setup by watching one full cycle rather than trusting the confirmation screen. A card autopay that fails because the bank account was short can still count as a late payment.
If money is genuinely tight, call the creditor before the due date, ask about a hardship program, and ask whether a smaller arrangement is reported as on-time. The CFPB has guidance on what to do when a payment cannot be made.
4. Reduce Card Balances: The Fastest Way to Improve Your Credit Score
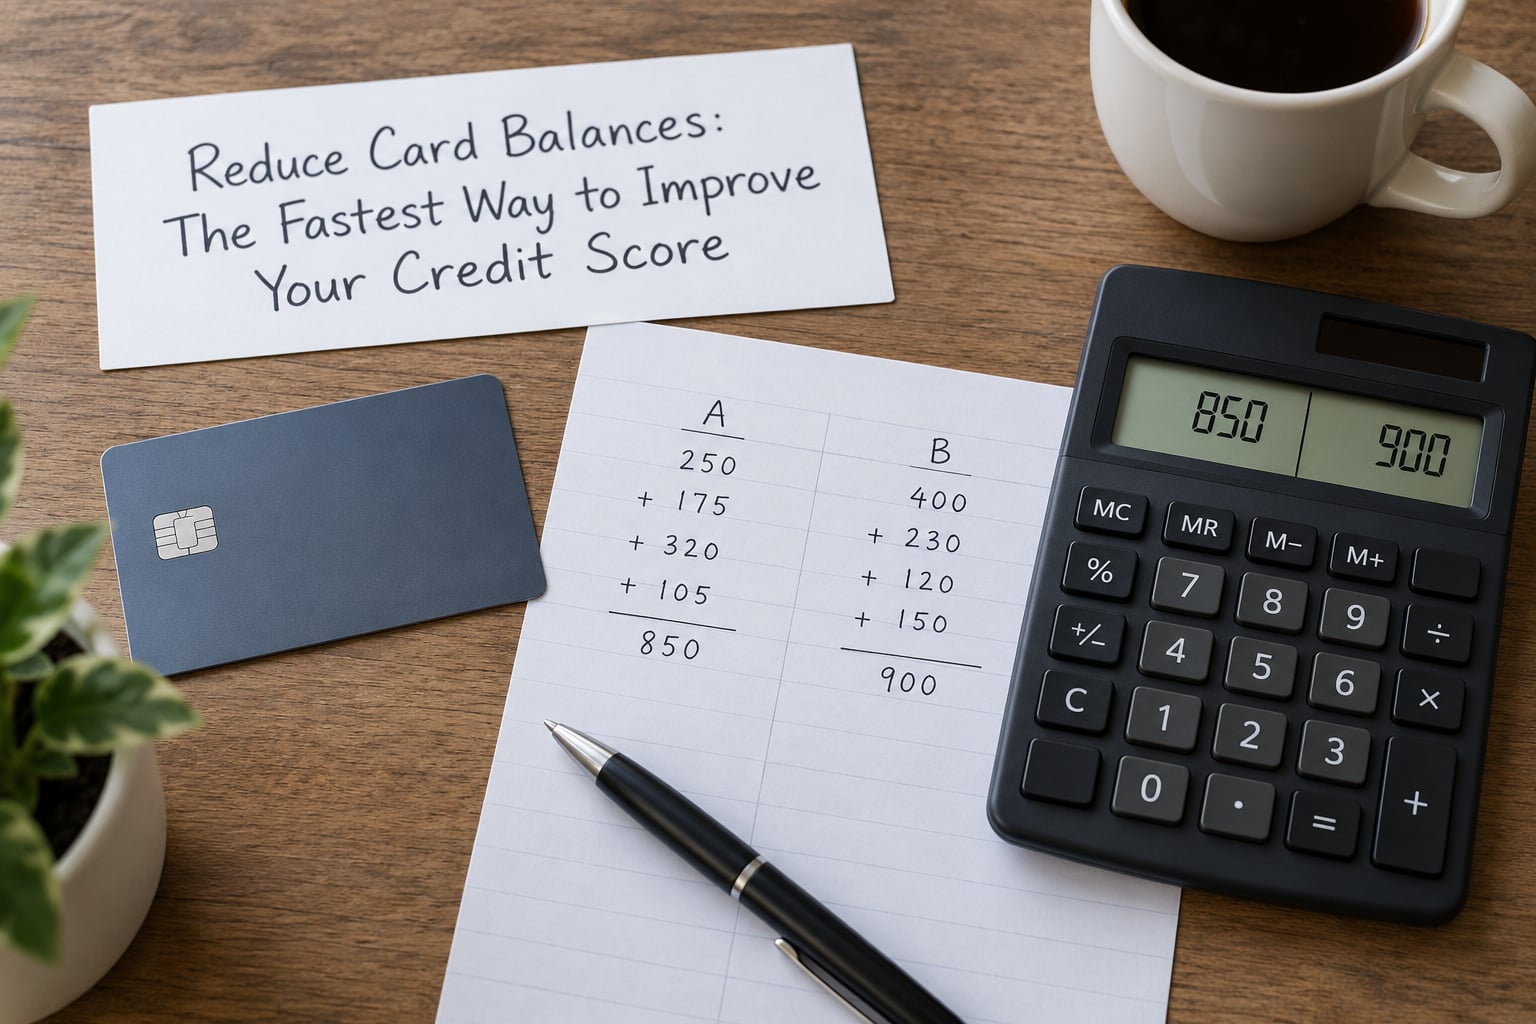
Credit utilization is your reported balances divided by your total credit limits, and it usually gets compared both to each card’s own limit and to your combined total. What shows up on your report is the statement balance, not your daily balance, so timing matters more than people expect.
Here is the arithmetic. Two cards carry limits of 1,500 and 2,500, a combined 4,000. If the first card reports 900 and the second reports 300, you are at 1,200 of 4,000, which is 30 percent on the combined figure but 60 percent on the smaller card. Pay the 900 down to 200 before the statement closes and the reported number becomes 500 of 4,000, under 13 percent.
There is no single target that suits everyone. Lower is generally better for the score, while the practical job is getting well below whatever level your balances have been sitting at.
5. Use a Small List of Credit Responsibly
If you have no history at all, three routes work. A secured card requires a deposit that sets your limit, and some issuers charge an annual fee. A credit-builder loan splits a small loan into monthly payments that get reported as you repay. Being added as an authorized user on a card someone you trust has open can build history quickly, though not every issuer reports authorized-user accounts to all three bureaus, so ask first.
None of these is free of risk. A secured card still reports, and the deposit limits your loss only if you stop using it. Authorized-user accounts carry a real risk if the primary holder charges the card without telling you. Keep the list to two or three accounts you can pay in full.
6. Request a Limit Increase When It Fits Your Situation
A higher limit lowers utilization without a new application, and many issuers process a limit increase as a soft pull or as no inquiry at all. The trade-off is a longer runway to overspend, and some issuers review income and account history before approving.
Use a request when your utilization is high because you travel or have seasonal expenses, not as a trick to rescue a score in a rush. Applying for several new accounts inside a short window is the fastest way to hurt the new credit factor, since each application can leave a record that stays on file for a couple of years.
7. Wait for Results and Prevent New Negative Entries
Accurate information updates on each bureau’s own schedule, and 30 to 60 days is common before a change shows up. Disputes take longer, often 30 to 45 days per investigation, and identity theft cases can run much longer.
Check your statements monthly and your reports annually instead of watching a score that refreshes daily. Frequent self-checks are soft inquiries and do not hurt you, but the daily swings are mostly noise from the reporting cycle rather than anything you did.
Common Mistakes
Closing your oldest card. It removes a chunk of total limit and shortens your history. Keep it open, and ask the issuer for a lower limit instead if you are worried about overspending.
Applying for several cards at once. One application you need is reasonable. Three in a month reads as risk to any model.
Paying a collection without getting it removed. Get the agreement in writing first, confirm the account shows a zero balance, and check back after the next cycle to see the negative entry is gone.
Paying only the minimum. Interest accrues and reported balances stay high. Paying in full every month is the single habit that keeps the amount owed factor down.
Carrying too many cards. More accounts mean more chances for a missed payment and harder to track. A small list you pay in full beats a large one you rotate.
Paying for score-fixing services. Genuine repair involves disputing real errors, which you can do yourself for free. Anyone promising to remove accurate negative information, or asking for upfront payment before doing anything, is not offering repair.
How to Maintain Your Credit Score After the 90 Days
After the 90 days, the work becomes a short routine rather than a project. Check statements once a month and look at the reported balance before the statement date closes, not on the payment due date.
Pull your reports once a year, in the same month each time, and read the account list. Set a recurring reminder in your calendar so it does not slip, and put any new account on autopay the day you open it.
Consider a free security freeze at each bureau after your review. A freeze blocks new credit in your name until you unfreeze it, and it does not affect your score or cost anything. A fraud alert is a lighter option that stays in place about a year and needs renewing.
A simple written budget you can follow beats a paid score-monitoring subscription. The free reports and free score estimates from the bureaus cover what most readers need, and money spent on a subscription does not raise a score by itself.
Frequently Asked Questions
How long does it take to improve a credit score?
Most readers who fix errors and lower their balances see movement in 30 to 60 days, because that is when bureaus typically refresh accurate data. Larger repairs take longer, and a score in the 500s moving to the 700s usually takes six to twelve months of consistent on-time payments and low balances. Anyone promising a 100-point jump in 30 days is selling something.
What is the fastest way to improve a low credit score?
Two things move a low score fastest. First, correct errors and dispute them, because a removed collection or wrong account can shift the number within a month. Second, drop reported balances before your statement date closes, since utilization carries about 30 percent of the weight. After that, on-time payments and time do the rest, and no shortcut replaces them.
Does checking my own credit score lower it?
No. Checking your own report or score is a soft inquiry and does not affect your score. Only a hard inquiry, which happens when you apply for credit and are approved, is recorded. Hard inquiries carry a small weight and stay on file for about two years, so apply when you need credit, not to test the system.
Are paid credit repair services worth it?
Rarely. Genuine repair means disputing real errors, which you can do yourself at no cost through the bureaus and the CFPB. Be cautious of anyone who wants payment upfront, promises to remove accurate negative information, or tells you to create a new credit identity with an EIN. Those practices are illegal or ineffective and can leave you with fresh problems.
Will paying off collections and charge-offs improve my credit?
Paying reduces what you owe and can help over time, but it does not automatically delete the negative entry. Ask the collection agency for the payoff figure in writing, pay, request removal of the entry, then verify on your next report. Some agreements are structured so the account updates as paid, and payment is worth considering alongside your other options.
Start where this guide starts: pull your three reports at AnnualCreditReport.com and read them side by side. If a line item is wrong, get that corrected before you worry about anything else, because every later step works from an accurate picture.